September 3, 2026
zebratech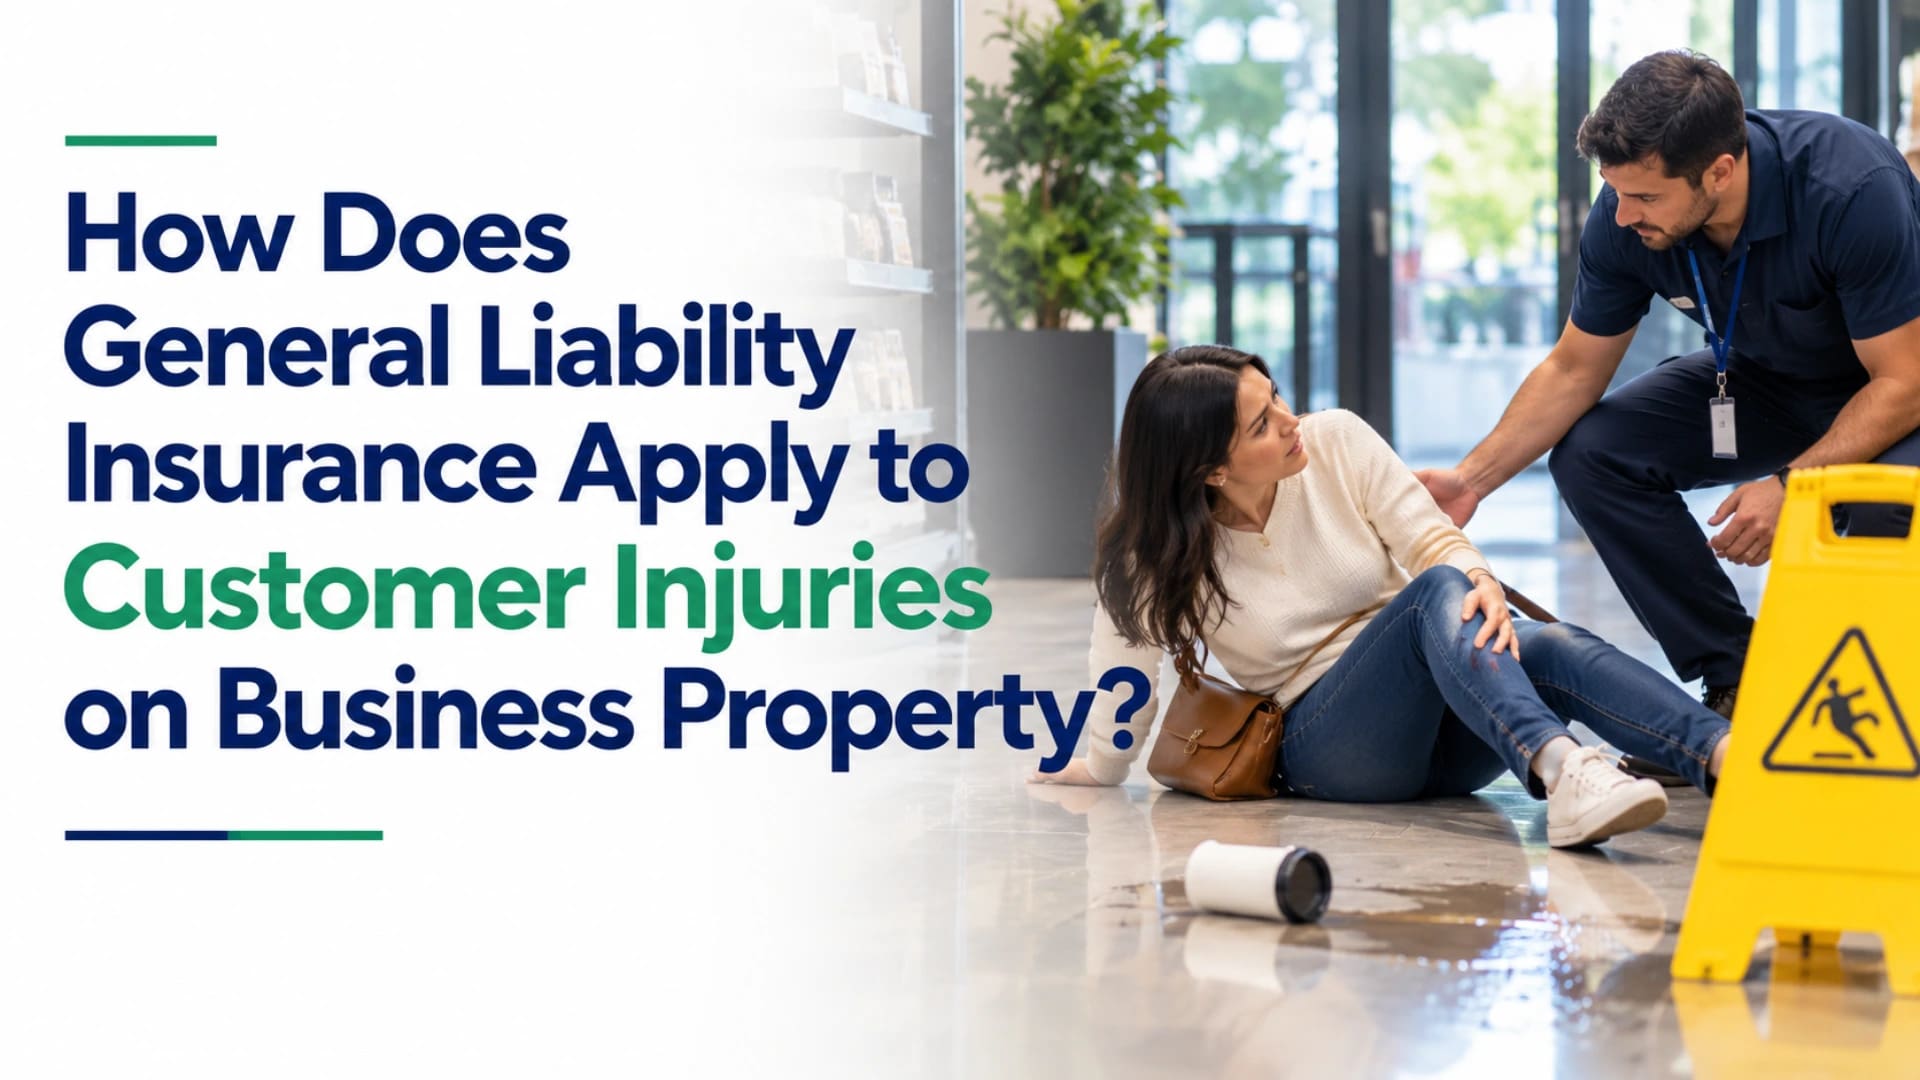
How Does General Liability Insurance Apply to Customer Injuries on Business Property?
A customer slips on a wet floor. Someone trips over an obstruction. A product falls from a shelf and causes an injury. These situations can happen even when a business owner is doing their best to keep the premises safe.
But what happens when a customer gets hurt on your property? Could your business be held responsible for their medical costs or other losses? For Santa Barbara business owners, understanding this risk is important.
This is where General Liability Insurance in Santa Barbara, CA may help. It can provide coverage for certain third-party bodily injury and property damage claims, depending on the policy terms, exclusions and limits.
What Happens When a Customer Is Injured at Your Business?
The situation can become complicated when a customer is hurt or gets injured on your premises. The customer may need medical attention and, in the future, may allege that the business did not keep a reasonable level of safety in its premises.
For example, imagine a café customer slipping on a wet floor that was not properly marked. A retail shopper might trip over an obstruction in an aisle. At a professional office, a visitor could fall because of an unsafe condition on the premises.
This does not necessarily mean that the business is liable. Nevertheless, should negligence or any other liability exposure occur, the costs related to the defence of the business or resolving the claim could arise.
So, having proper insurance coverage is very important here. Even the California Department of Insurance describes commercial general liability as coverage addressing liability exposures involving bodily injury or property damage to third parties.
How Can General Liability Insurance Respond?
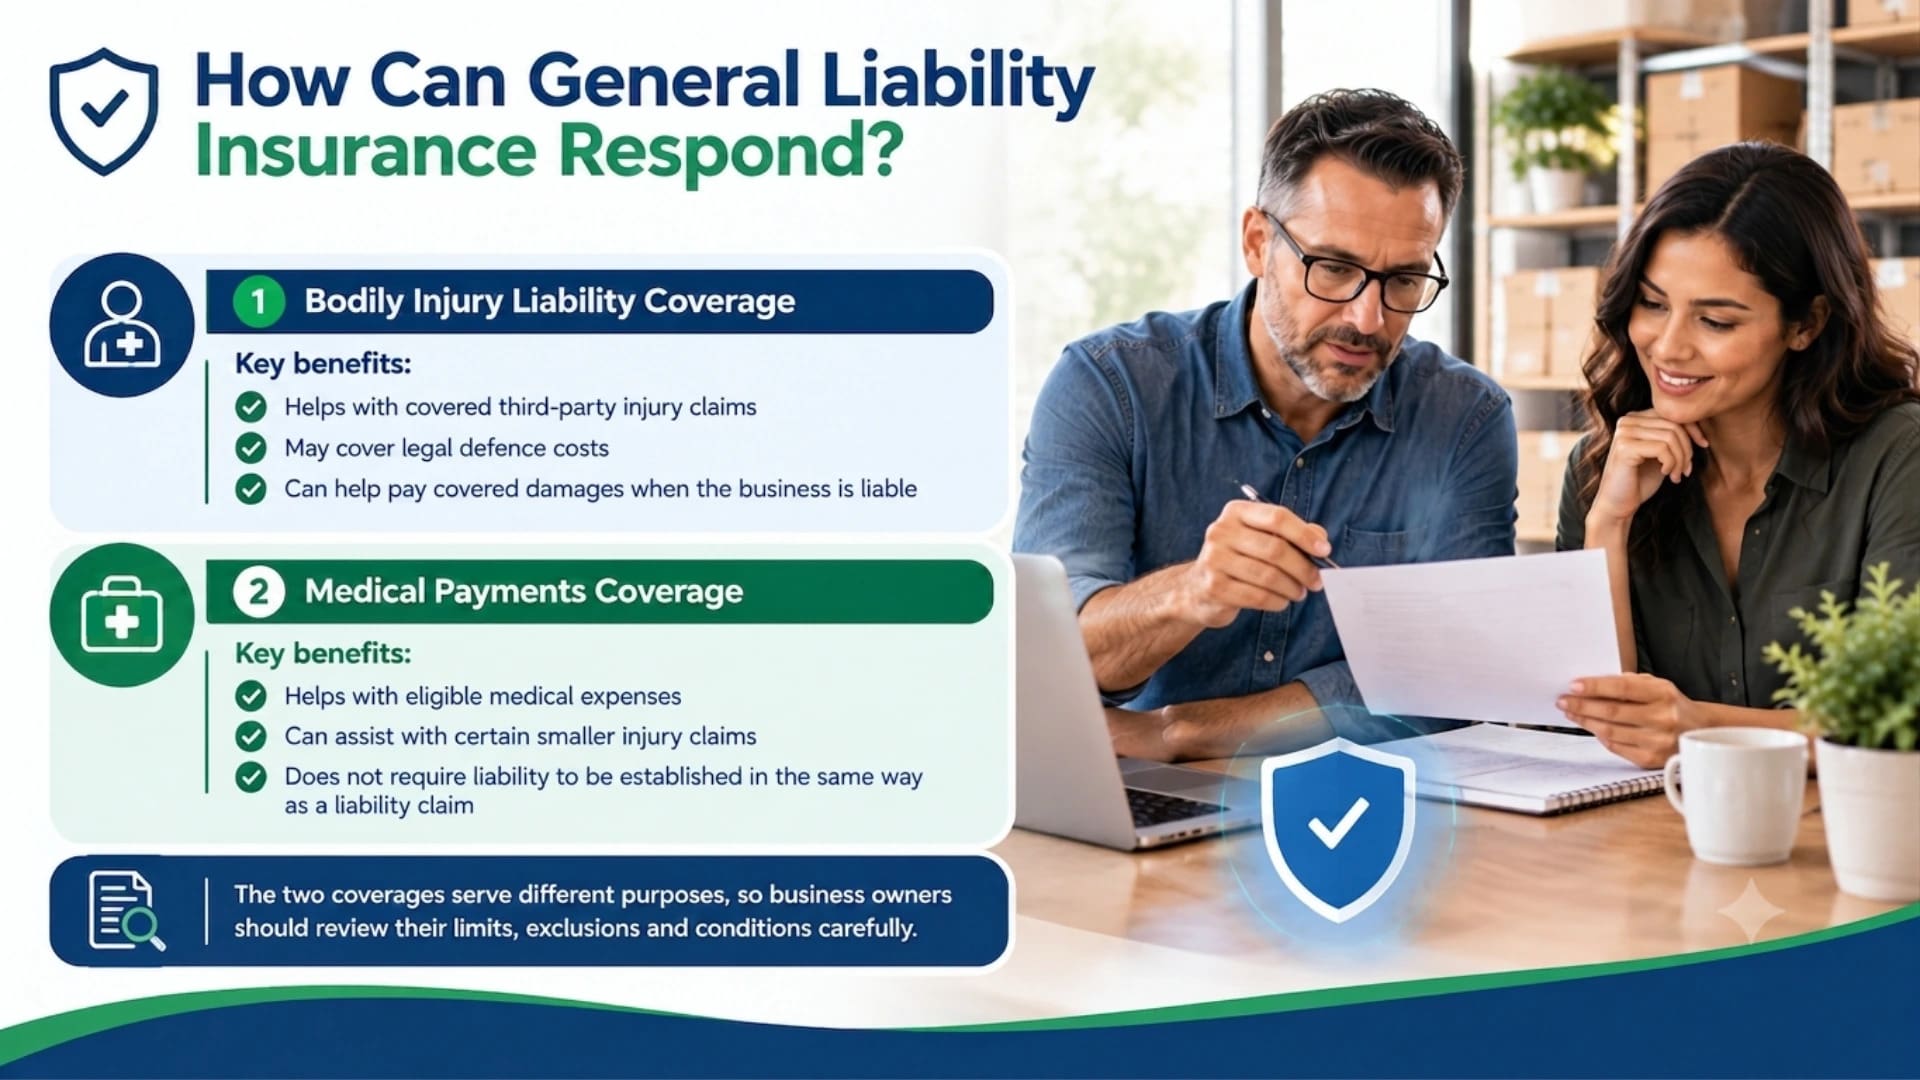
When a customer is injured at a business, general liability insurance may respond in different ways. Two areas are particularly relevant: bodily injury liability coverage and medical payments coverage.
They serve different purposes and should not be treated as the same protection.
1. Bodily Injury Liability Coverage
This coverage may apply when a business is legally liable for an injury sustained by one of its customers. If a client gets injured due to an unsafe situation within the business premises, this coverage may help cover eligible legal defence costs and damages, subject to the policy limits and exclusions.
Key benefits:
- Helps with covered third-party injury claims
- May cover legal defence costs
- Can help pay covered damages when the business is liable
2. Medical Payments Coverage
Medical payments coverage can help pay certain medical expenses for accidental injuries involving non-employees, without requiring the business to be found legally liable. Coverage is subject to the policy’s terms and limits.
Key benefits:
- Helps with eligible medical expenses
- Can assist with certain smaller injury claims
- Does not require liability to be established in the same way as a liability claim
The two coverages serve different purposes, so business owners should review their limits, exclusions and conditions carefully.
What Are the Common Customer Injury Scenarios for General Liability Insurance
Customer injuries can happen in businesses that appear relatively low-risk. Some common examples include:
- A visitor slips on a recently mopped floor.
- A customer trips over damaged flooring or an unexpected obstruction.
- Merchandise falls from a display and injures a shopper.
- A customer is injured because of an unsafe condition in an area accessible to the public.
The broader point is that premises liability is not limited to one type of business. Restaurants, retail stores, salons, offices and other customer-facing businesses can all have situations that deserve attention.

What Should You Do After a Customer Injury?
When an injury happens at your business, the priority should be ensuring the safety of the individual and providing proper medical help.
After that, practical documentation can become important. Business owners should consider:
- Recording the time and location of the incident.
- Taking photographs of the location along with its conditions.
- Locating any witnesses and recording their contact details.
- Collecting any evidence such as security footage from the scene.
- Reporting the incident immediately to the appropriate insurance representative.
- Avoiding assumptions or unnecessary statements about who was at fault.
Why the Right Liability Coverage Matters
Having business insurance is only part of the equation. The more important question is whether the coverage actually reflects how the business operates.
This is when it is helpful to consult with licensed insurance agents. Instead of choosing insurance according to a standard checklist, the business owner can talk about the specifics of the operation.
In Conclusion
Customer injuries can expose a business to unexpected claims and costs. Reviewing liability coverage in advance can help ensure the policy reflects the risks involved in your day-to-day operations.
As an independent insurance agency, CoreGen Insurance Agency, LLC, can help you look beyond basic coverage and identify options that fit your business and its liability exposures.
Reach out to our team to review your current coverage and explore ways to protect your business against unexpected customer injury claims.